How long to pay off 210k?

Started by ldiot
This forum made possible through the generous support of SDN members, donors, and sponsors. Thank you.
Get help with your application

Use all the free resources available to you from SDN: articles, guides, expert advising, forums discussions, and school research.

ldiot

Full Member
7+ Year Member
Advertisement - Members don't see this ad
Is it realistic to expect to pay 210k in less than 5 years?

4k a month will pay it in 5 years

Assuming 6,100 take home pay per month
1k on rent
200 on gas
500 on food/household supplies
60 for phone
300 for miscellaneous stuff that I'm forgetting like clothes/gym membership

That pretty much leaves me with 4k left

I'm thinking rather than trying to cut expenses even further just to save 200 dollars it would be more worthwhile to try to pick up an extra shift every week or two if I want to pay beyond 4k.

With all that being said I haven't got my official offer yet (I'm hoping close to 6500 but could be as low as 6000 I really don't know) and don't know if extra hours are realistic either

My interest, as a weighted average is 5.8%. I'm thinking I could consolidate after a year with someone like SoFi to bring it down, but in the grand scheme of things it's going to save me a month max

Depressing
 
Many others have done it, but the strong consensus is if your offered a job do two things:

1) contribute to any match the company may offer in a 401k

2) Build an emergency savings (6 months is great, but I’d personally aggressively save to at least 3).

I feel like we just had a big discussion with another user about 4K monthly payments being the magic number.

**Edit** Found it: Some info on this may help. Your situation is slightly different but maybe feedback on this will give you an idea of what to expect (before it goes off topic toward the end).

Is paying $4,000/month in student loans good enough?
 
Last edited:
A good estimate is the principal divided by 25% of your takehome income. You can alter that up if you wish, but that's the general floor. As well as what @BC_89 says. More than 60% of your take home (before rent and other expenses) is rather high and takes major discipline.

Not to add to your depression, but if you're going to work every extra shift you can possibly do for your first couple of years, you will be too busy to spend money which surprisingly helps. That was my trick in grad school...

On the other hand, based on what you've written elsewhere, there is something to be said for mental health recovery. Maybe take it at a regular pace for at least six months until you have some morale recovery from UF.
 
Advertisement - Members don't see this ad
Is it realistic to expect to pay 210k in less than 5 years?

4k a month will pay it in 5 years

Assuming 6,100 take home pay per month
1k on rent
200 on gas
500 on food/household supplies
60 for phone
300 for miscellaneous stuff that I'm forgetting like clothes/gym membership

That pretty much leaves me with 4k left

I'm thinking rather than trying to cut expenses even further just to save 200 dollars it would be more worthwhile to try to pick up an extra shift every week or two if I want to pay beyond 4k.

With all that being said I haven't got my official offer yet (I'm hoping close to 6500 but could be as low as 6000 I really don't know) and don't know if extra hours are realistic either

My interest, as a weighted average is 5.8%. I'm thinking I could consolidate after a year with someone like SoFi to bring it down, but in the grand scheme of things it's going to save me a month max

Depressing

Assuming 6,100 take home pay per month
0k on rent (live in trailer behind car) although average rent around me is 2k+ a month for a studio
400 on gas
900 on food eating out
0 for phone (use Wifi to make calls, or tell ppl to call you at work)
30 for gym membership to shower

I think you could pay that off in 2 years if you wanted to. You would have to stop eating out and instead just eat rice and beans though.

I don't eat out anyways, and my car is paid off, but even if I put 100% of my take-home pay to loans it would take more than 2 years lol
 
I agree with above posters, first build up at least a few months of emergency fund and contribute up to the match for your employer 401k. That is a tight budget for 5 years but doable, especially if you cut rent down more, depending on your region and willingness to add a roommate.

Maybe you don't need a big emergency fund if you have a great financial safety net with rich parents but with 200k in debt I am doubting that is the case.

Well my car is paid off and I am always welcome to move in with them, but they couldn't support my loan payment.

I'm going to use my grace period to build my safety net.

I was thinking of putting my loans on the 25 year plan, that way I can direct a higher percentage of the 4k towards the highest interest loan. Not sure how much it would save me though
 
OP what hourly rate and hours per week are you expecting? According to recent threads a lot of new grads get around $56-59/hr with less than 40 hours, usually around 32. After taxes, insurance, 401k, HSA... 6k take home seems ambitious.
 
It depends on your situation and what you plan on sacrificing. There are other unplanned expenses that come up that you have no control of either so I wouldn't be safe to go paycheck to paycheck without any sort of money left over. Are you married? kids? plans for marriage/kids within 5 years? Unplanned car maintenance. Any plans for vacation within those 5 years to keep your sanity? I'm not saying you can't do it with that budget but just reminding you of other things to keep in mind.
 
Assuming 6,100 take home pay per month
0k on rent (live in trailer behind car) although average rent around me is 2k+ a month for a studio
400 on gas
900 on food eating out
0 for phone (use Wifi to make calls, or tell ppl to call you at work)
30 for gym membership to shower

I think you could pay that off in 2 years if you wanted to. You would have to stop eating out and instead just eat rice and beans though.

Might as well just sleep in the break room if you are going to combine work life with non-work life and live off of break room snacks & food employees will bring in on occasion (donuts, bagels, cakes, etc.). No need for gym membership, plenty of lifting doing truck & plenty of cardio spinning your wheels in the pharmacy (just need to redesign/remodel area to make a track layout).

#modest_anteater way of life...

No, not only are most pharmacies not zoned for humans sleeping in but also it would probably violate their insurance contract having someone sleep there. Also i hide my home-free status from all employers and coworkers due to the potential for discrimination.
 
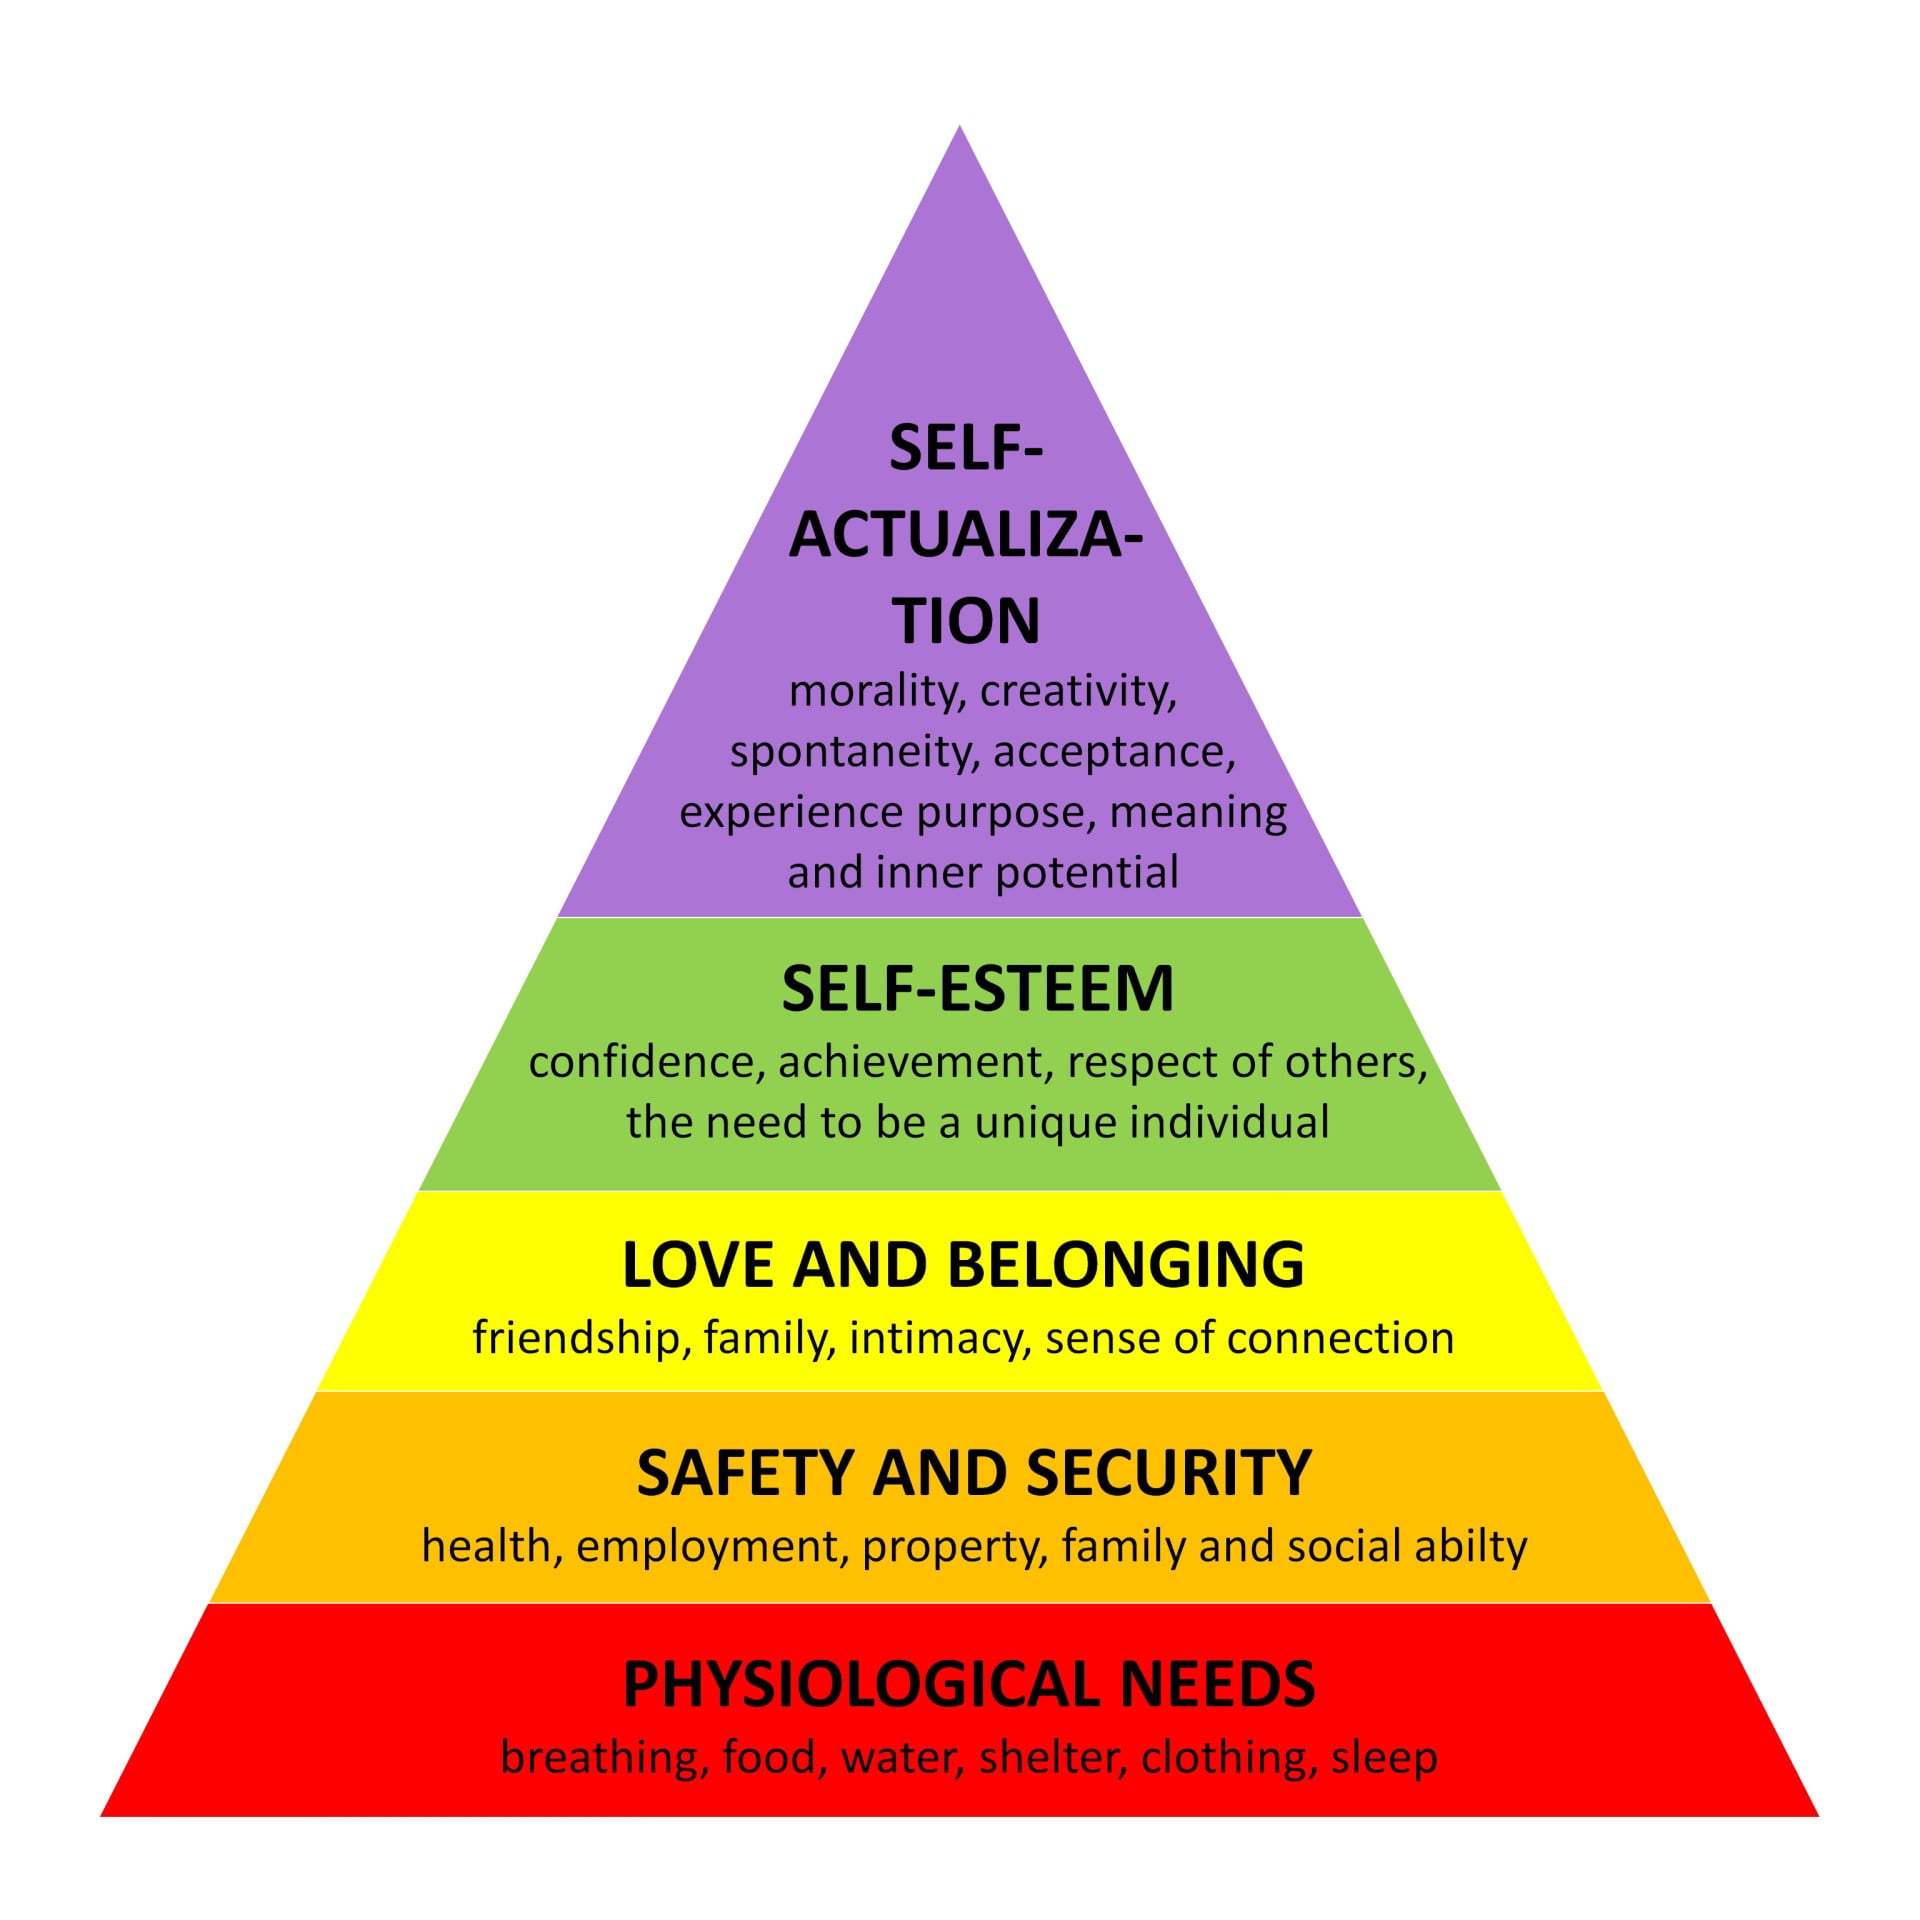
maslow-5.jpg
 
OP what hourly rate and hours per week are you expecting? According to recent threads a lot of new grads get around $56-59/hr with less than 40 hours, usually around 32. After taxes, insurance, 401k, HSA... 6k take home seems ambitious.

I plugged in $52.50 per hour, 40 hours a week = ~110,000/year, with an effective tax rate of 32% that would be $6,200 take home before insurance. How much does a high deductible plan cost? I was thinking 52.50 was pretty conservative, I talked to graduates last year getting 58-60. 58 dollars would put me at 6850 a month

And I know I'm not accounting for 5% to get my match either
 
Last edited:
Advertisement - Members don't see this ad
Maybe you should wait until you get your offer letter... Don't want to jinx anything but there is that possibility you might not get an offer or float for part time hours.
 
HDHP is 29/pay period for me. However you will likely pay a lot for anything that is not routine even at insurance-negotiated rates.
 
I plugged in $52.50 per hour, 40 hours a week = ~110,000/year, with an effective tax rate of 32% that would be $6,200 take home before insurance. How much does a high deductible plan cost? I was thinking 52.50 was pretty conservative, I talked to graduates last year getting 58-60. 58 dollars would put me at 6850 a month

And I know I'm not accounting for 5% to get my match either

I make a bit over $67/hour and 40hrs/week. After taxes, insurance, max 401k with 2 dependents and I take home maybe $3,300 every 2 weeks without extra shifts or $6,600/4wks. Unless you don't have state income tax. Don't forget social security tax and dental/vision insurance also.
 
I graduated May 2015 with ~225k. Current balance is 108k. So I've paid 117k plus interest in 3 years. So ~ $3,500/ month. Currently paying 2k/month. There were months I got mad at the interest I was paying and dumped savings towards the loans. I hope to have this paid off in another 3 years. I am currently sitting on 35k in my ally savings, not sure what to do with. Pay loans or invest? Loans @ 3.15% Fixed.
 
Follow @Modest_anteater

Definitely doing this if I am pressed for money... hella fun + tons of experience and you get to save a tons of money $1-2k/month easily.

 
Follow @Modest_anteater

Definitely doing this if I am pressed for money... hella fun + tons of experience and you get to save a tons of money $1-2k/month easily.


Yeah IDK how well my life would work for a single woman. I already get a lot of creepy guys around as it is. Pretty sure it would be a lot harder if you were a single woman and 1000x if you were single, attractive, young and thin like that girl. She prob wouldn't last a month where I live due to the constant sexual harassment/attention.
 
Yeah IDK how well my life would work for a single woman. I already get a lot of creepy guys around as it is. Pretty sure it would be a lot harder if you were a single woman and 1000x if you were single, attractive, young and thin like that girl. She prob wouldn't last a month where I live due to the constant sexual harassment/attention.
There are multiple attractive vanlife women YouTuber that make it work.
 
refinanced from 6.5% of 214k debt to variable 3.2% rate (which has increased to 4.55% now).

Began to aggressively pay it down since September, after I first entirely paid off my wife’s 130k student debt (her’s was higher interest and she is still in training at 60k salary).

Now still have 91k remaining

Debt freaking sucks

799E25DF-631C-493D-9BA5-7D621148C75F.png
 
I graduated May 2015 with ~225k. Current balance is 108k. So I've paid 117k plus interest in 3 years. So ~ $3,500/ month. Currently paying 2k/month. There were months I got mad at the interest I was paying and dumped savings towards the loans. I hope to have this paid off in another 3 years. I am currently sitting on 35k in my ally savings, not sure what to do with. Pay loans or invest? Loans @ 3.15% Fixed.

depends on interest rate hikes, but if a 30 year mortgage is going 5-5.25, many would say hang on to the the 3.15...
 
There are multiple attractive vanlife women YouTuber that make it work.
I strongly believe these to be posers. They prob live in hotels and then only get in their vans when they are on video. The only women i have met in vans were over 60 yo and with their bf/husbands.
 
refinanced from 6.5% of 214k debt to variable 3.2% rate (which has increased to 4.55% now).

Began to aggressively pay it down since September, after I first entirely paid off my wife’s 130k student debt (her’s was higher interest and she is still in training at 60k salary).

Now still have 91k remaining

Debt freaking sucks

View attachment 244784

That' really impressive, over 100k in a year. Did you have savings that you dumped in or did it comes from wife's salary?
 
That' really impressive, over 100k in a year. Did you have savings that you dumped in or did it comes from wife's salary?

The most recent payment used 20k of savings plus 20k of the income

Our monthly pretax gross income is a bit over 50k.
After paying taxes and maxing out our 401k, HSA, 457, IRA we only have about 26 to 27k to spend. Have decided to up the monthly payment to 20k/month which will shrink our budget to 6k spending for awhile.
 
I paid off $50k in student loans and a $310k mortgage in 8 years, so that averages $45k in principal every year. Being frugal and throwing all my spare money at the loans was only part of it. The other part was putting $20-30k/yr of my salary into taxable investments FIRST such as ESPP and Vanguard index funds. I waited until they made a nice 20-50% profit which was sometimes 2-3 yrs, then sold them and used the original amount plus the profits to pay down the loans in large $50-100k chunks.

This method ensures that you don't miss out on gains in the stock market, which are fairly certain over periods of 5-8 yrs. At the same time the market is very volatile +/- 50% so it also ensures that you take some profits out when the market is up.
 
Advertisement - Members don't see this ad
30% of government assets are student loans of which 40% are in default. It has been studied and deemed an "unsustainable situation". Talk to a student loan lawyer about it like i did.My advice? Pay as little as you can now as you go. They will be cutting deals at some point, there is no other way. somewhere around 2025 is what is estimated. They have sunk an entire generation into horrifying debt that will trickle down forever if it is left unchecked. They really need to stop loaning this money out and fast. I cant understand how the government does not see this coming?

If you pay EVERYTHING you can now and what i say is true, then you have thrown away a lot of money you didnt have to. And by 2025 you will have very little savings when the economy collapses, so you can leave the country or whatever your hunker down plan is.....

Just think logically for a moment and ask yourself.....how long can this really go on before so many people are defaulting that it disrupts the entire system? it's not a matter of IF its a matter of WHEN....
 
I paid off $50k in student loans and a $310k mortgage in 8 years, so that averages $45k in principal every year. Being frugal and throwing all my spare money at the loans was only part of it. The other part was putting $20-30k/yr of my salary into taxable investments FIRST such as ESPP and Vanguard index funds. I waited until they made a nice 20-50% profit which was sometimes 2-3 yrs, then sold them and used the original amount plus the profits to pay down the loans in large $50-100k chunks.

This method ensures that you don't miss out on gains in the stock market, which are fairly certain over periods of 5-8 yrs. At the same time the market is very volatile +/- 50% so it also ensures that you take some profits out when the market is up.
WELL. it's different if you are not undergoing reproductive starvation. For us men that have still not found a mate in our 30s and 40s we need to spend every spare penny we have to impress women to get one to be our future wife so we don't really have excess money to pay down debts and such.
 
30% of government assets are student loans of which 40% are in default. It has been studied and deemed an "unsustainable situation". Talk to a student loan lawyer about it like i did.My advice? Pay as little as you can now as you go. They will be cutting deals at some point, there is no other way. somewhere around 2025 is what is estimated. They have sunk an entire generation into horrifying debt that will trickle down forever if it is left unchecked. They really need to stop loaning this money out and fast. I cant understand how the government does not see this coming?

Cite or ban.

That's right you can't because your citation is false. Here is the most recent data from September 2018.

National Student Loan Cohort Default Rate Falls | U.S. Department of Education

The FY 2015 CDR represents the lowest national cohort default rate since the three-year rate was first released in 2012.

The joking joke for the millennials (and I'm one) on Reddit and SDN where they constantly whine about the student loan burden is that you will pay every last god damn red cent back. Even if it takes you 30 years. Sure, you can pay 10% (RE)PAYE++ or whatever joke program for 25 years or hope you cross your T's and dot your I's and PSLF will come through, but every last cent will be paid back legally.

There will be no student loan write down.

Hey man take it easy, I said MY LAWYER gave me this info. period. perhaps she was mis-informed. but i would double check, shes pretty sharp and helped me out a lot. I still dis agree however, student loan debt is a REAL problem, its not just going away. And various agencies report all sorts of whacked out statistics. just wait until 2025 and see if i was right? ok.
 
I got a full time staff 56/hr, can we resvisit it now?
Wow, congratulations! I assume FL, so use a paycheck calculator for the number of hours. Net pay per week is 1767 without further deductions for roughly 92k a year. Take 2k out for proper health insurance and that's your starting budget.

Free Paycheck Calculator — Hourly and Salary Employees | QuickBooks

Realistically, 30k per annum should be straightforward on an FT budget living at home without further major expenses. In year one, I understand the debt anxiety, but you need to build up 30k in liquid assets as a recession savings fund. I'd also put in the full 401k amount as it'd be around 14k with the tax kickback to 18 or 19. If you go with you expense numbers around $24k, then adjust accordingly but still manageable living the middle class life.

Year 2 and onwards, you can then go for the higher payoff percentages on your loan.
 
Last edited:
I got a full time staff 56/hr, can we resvisit it now?
1k on rent
200 on gas
500 on food/household supplies
60 for phone
300 for miscellaneous stuff that I'm forgetting like clothes/gym membership

That pretty much leaves me with 4k left

I'm thinking rather than trying to cut expenses even further just to save 200 dollars it would be more worthwhile to try to pick up an extra shift every week or two if I want to pay beyond 4k.

With all that being said I haven't got my official offer yet (I'm hoping close to 6500 but could be as low as 6000 I really don't know) and don't know if extra hours are realistic either

My interest, as a weighted average is 5.8%. I'm thinking I could consolidate after a year with someone like SoFi to bring it down, but in the grand scheme of things it's going to save me a month max

1k on rent - try to get a roommate to drop this around $650-750
200 on gas
500 on food/household supplies -> way too much on food. I spend $150/mo if I don't eat out.
60 for phone -> drop this to 15/mo, use Mint mobile 3GB plan for $15/mo. It runs under Tmobile network.
300 for miscellaneous stuff that I'm forgetting like clothes/gym membership - too high, you should not pay more than $30/mo for gym

Besides that, mine looks like:
Car Ins 46/mo 100/300/50 liability only
AAA membership 4.2/mo
Clothing 5/mo
Gift and donation 30/mo
Personal care 15/mo
MISC 30/mo
Amazon/Netflix account Free (friends')

$56/hr = 116.5k/yr gross
Take home :
After maxing 401k $730 pre-tax/2 weeks = $2505/2 weeks (CA - in a high state tax)
If no state tax = $2755/2 weeks

$65-72k take home depending on where you live. As long as you keep your expenses below $1.5k/mo (easier said than done), you can pay $4k/mo to student loans. Do NOT skip maxing 401k contribution, it's free money match, you can't backtrack the year you miss and it lowers your taxable income. No one cares if you delay paying off your student loan by 6 months paying your future self first.
 
You can do it. I started with 156k and it will be paid off in 30 months from when I started (8 months about to go).
 
Last edited: